Scholarly Shariah ReviewDr. Humayun Dar is a respected Islamic finance scholar, and his efforts to introduce innovative ideas deserve appreciation. However, innovation in Islamic finance must also be examined carefully from a Shariah perspective. In this spirit, I felt it necessary to highlight certain Shariah concerns in the proposed model for constructive scholarly discussion and further refinement.
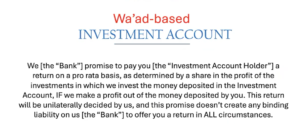
Snapshot from Dr. Humayun Dar’s Presentation
My Juristic Analysis on the Proposed Waʿd-Based Investment Account
Dr. Muhammad Abubakar Siddique
The proposed structure appears to involve two fundamental components, both of which require separate Shariah analysis:
- The placement of funds by the customer with the bank: Under which contract does the customer deposit the money with the bank—Qard, Amanah/Wadiʿah, Mudarabah, Wakalah, or some other recognized contract?
- The unilateral promise by the bank to pay a return: Once the nature of the deposited funds is established, the Shariah validity of the bank’s promise to provide an additional return must then be examined.
1. Underlying Contract of the Deposited Funds
The first and most fundamental issue is that the proposed product does not clearly explain under which Shariah contract the customer’s money is received by the bank.
Merely transferring money to the bank has no independent contractual status in Islamic jurisprudence. The transaction must necessarily be attributed to a recognized legal relationship. Calling the product a “Waʿd-Based Investment Account” does not solve this issue because a Waʿd is only a promise; it is not the underlying contract governing the receipt, use, ownership and repayment of the customer’s funds.
Moreover, this product apparently intends to operate as an alternative to Mudarabah. Therefore, if it is not Mudarabah, it must be clarified whether the funds constitute Qard or Amanah.
العبرة في العقود للمقاصد والمعاني لا للألفاظ والمباني
The principle is directly relevant here: the Shariah characterization depends upon the substance and economic reality of the transaction, not merely upon the terminology used.
If the bank:
- receives the customer’s money,
- is permitted to use and invest it,
- becomes liable to return the principal, and
- the customer does not bear the normal investment loss,
Then the substantive nature of the relationship appears to be Qard.
It cannot reasonably be treated as a pure Amanah while the bank is freely using the funds for its own investment activities and simultaneously guaranteeing their repayment.
2. The Bank’s Unilateral Promise of Return
Once the underlying relationship is identified as Qard, the second issue becomes more serious.
The product description clearly states:
“We [the Bank] promise to pay you…”
Therefore, the Waʿd is from the bank to the depositor, not from the depositor to the bank.
If the customer is effectively lending money to the bank, the structure becomes:
- the customer provides a loan to the bank;
- the bank guarantees repayment of the principal; and
- the bank makes an ex ante promise of an additional financial return if profit is generated from the use of those funds.
In such a case, describing the promise as non-binding does not necessarily remove the Shariah concern. The real question is whether the additional return is connected with the loan and is understood from the beginning as a benefit that may be received because the customer has provided funds to the bank.
There is a clear difference between:
- a borrower voluntarily giving something extra without any prior promise, condition, understanding or expectation; and
- an additional return that is incorporated into the product structure and communicated to the lender from the outset.
The present case appears closer to the second situation.
Accordingly, even if the promise is legally non-binding, the arrangement gives rise at minimum to a serious Shibhat al-Riba (شبهة الربا), because the lender is entering into the transaction with a structured expectation of an additional benefit linked to the loan. Shibhat al-Riba (شبهة الربا) is equally prohibited as riba itself in Shariah. Merely changing the additional payment from a contractual obligation into a non-binding promise does not necessarily change its substantive connection with the Qard.
Treatment of Loss
A further important issue is that the product description does not clearly explain who bears the investment loss.
Two possibilities arise:
- If the bank guarantees the principal and bears the investment loss, this further strengthens the characterization of the customer’s funds as Qard. In that case, an additional promised return connected with that loan creates a serious riba concern.
- If the customer bears the investment loss, then the relationship is no longer naturally characterized as Qard and must instead be structured under a genuine investment contract such as Mudarabah or Wakalah bil-Istithmar, with clearly defined rules regarding profit, loss and liability.
There is also some ambiguity between the statements that the return will be determined “on a pro-rata basis” from investment profit and that it will be “unilaterally decided by the bank.” The precise basis of the customer’s entitlement therefore also requires clarification.
Conclusion
Before proceeding further with this product, the following matters should first be clearly established:
- What is the underlying contract governing the deposited funds?
- Is the principal guaranteed by the bank?
- Who bears any investment loss?
- What is the exact basis for calculating the proposed return?
- What is the Shariah effect of the bank’s unilateral promise when the underlying relationship is a Qard?
The central Shariah concern is that Waʿd cannot substitute for the identification of the underlying contract. If the underlying relationship is ultimately Qard, then an additional return promised by the borrower to the lender—whether described as binding or non-binding—requires serious reconsideration from a riba and Shubhat al-Riba perspective.
October 05, 2026